India’s International Traffic - FY25 vs FY24
Here is the data. Share your analysis in the comments.
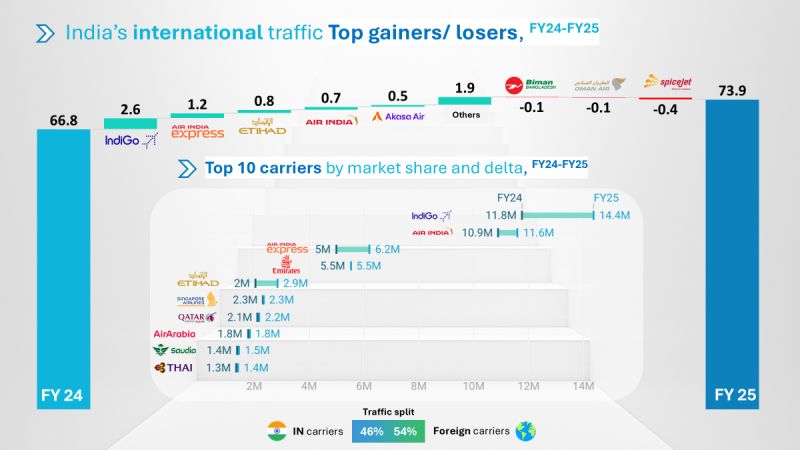
Total growth: +7.1M pax (+10.6%) → 66.8M → 73.9M
Indian carriers’ share: 46% (↑ from 44%) - gaining 2 p.p. YoY
Top Growth Drivers
🇮🇳 IndiGo: +2.6M (+22%) - 37% of total traffic gain
🇮🇳 Air India Express: +1.2M (+24%)
🇮🇳 Air India: +0.7M (+6%)
🇦🇪 Etihad: +0.8M (+40%) - biggest foreign gainer
🇮🇳 Akasa Air: +0.5M
AUH’s dual-carrier ecosystem, Etihad and Air Arabia Abu Dhabi, added nearly 1.0M incremental pax in FY25. (Bilaterals likely exhausted)
EY's absolute growth outpacing AI is notable (merger effect?)
Significant Foreign Gainers
🇦🇪 Etihad: +0.8M (+40%)
🇲🇾 Malaysia Airlines: +0.26M (+25%)
🇴🇲 SalamAir: +0.25M (+147%)
🇬🇧 Virgin Atlantic: +0.24M (+42%)
🇭🇰 Cathay Pacific: +0.17M (+25%)
🇹🇭 Thai AirAsia: +0.15M (+23%)
🇩🇪 Lufthansa: +0.20M (+17%)
🇨🇦 Air Canada: +0.08M (+26%)
🇻🇳 Vietnam Airlines: +0.06M (+48%)
🇹🇭 Thai Lion Air: +0.11M (+83%)
Major Declines
🇮🇳 SpiceJet: –0.44M (–24%)
🇴🇲 Oman Air: –0.11M (–8%)
🇧🇩 Biman Bangladesh: –0.10M (–49%)
🇸🇬 Scoot: –0.09M (–10%)
🇳🇵 Nepal Airlines: –0.05M (–25%)
(This write-up is for educational/informational purposes only; happy to amend inaccuracies, if any. Views are personal.)
DGCA’s Q4FY25 numbers are provisional; the dataset could contain minor variances.
First published on LinkedIn, see the original.All writing →