Oct-25 UPDATE - Wizz Air’s Saudi Play
Oct-25 UPDATE - Wizz Air’s Saudi Play: A Bold Entry, A Hard Lesson, and a Second Chance
In April, I wrote about how Wizz may have got its Saudi plot wrong.
In July, the airline announced the cessation of its Abu Dhabi ops and closure of its JV with ADQ.
Here’s a relook at its Saudi footprint, with key updates in the aftermath of the AUH exit and claims that certain routes could resume in Winter 2025.
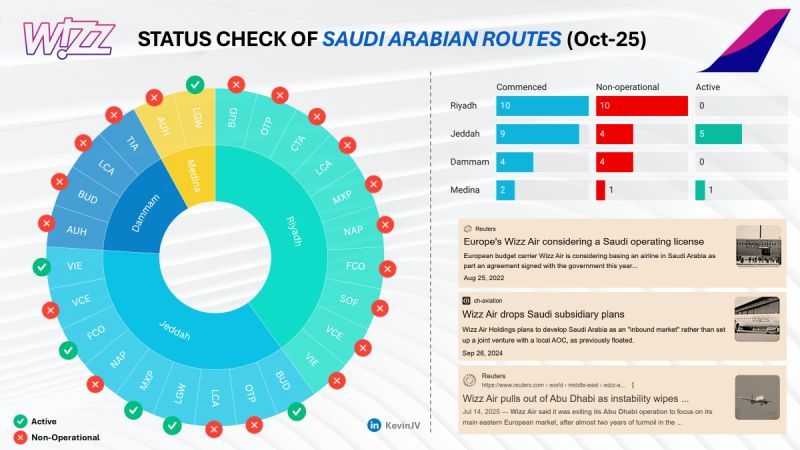
>One size doesn’t fit all, and the airline's Saudi strategy is a case in point. The entry was bold, but it lacked local calibration. Of the 25 routes launched, only 6 remain operational.
Riyadh: All 10 routes discontinued
Dammam: All 4 routes discontinued
Medina: 1 of 2 routes operational
Jeddah: 5 of 9 routes remain operational
The contrast is striking, complete withdrawal from Riyadh and Dammam, while Jeddah and Medina (the pilgrimage gateways) have sustained limited connectivity. (Do share your thoughts in the comments!)
The original plan to establish a Saudi AOC was quietly shelved, followed by rapid route reversals.
That said, Wizz Air’s new UK services to Jeddah and Medina is a smart pivot.
Consider this angle:
>35.7 million Umrah performers arrived in the Kingdom in 2024, including 16.8 million international pilgrims.
>The UK is home to 3.9 million Muslims (Roughly 6.5% of the population, based on the last census), with a median age of just 27.
>High concentration in London, Birmingham, Bradford, Manchester, and Leicester.
>A young, digitally native and price-sensitive demographic with both the intent and ability to travel.
There’s also a wider commercial argument for low-cost capacity. On routes like Riyadh–Rome, fares on Saudia (dated narrow body product) often range from SAR 2,500 to 3,000 round trip (~USD 650–800) pricing that leaves significant room for LCC or ULCC disruption, especially for non-premium, P2P pax. Wizz used to sell one-way tickets for as low as SAR 100. From a demand stimulation perspective, could it get any better?
Wizz is structurally well-positioned to address that gap, but it can't simply transplant a European model into a very different operating environment. For context, Wizz had the lowest CASK among European LCCs in FY24.
To succeed in the Kingdom, Wizz must at least:
1. Embrace a locally tuned strategy (incl. network, distribution, product, marketing and sales)
2. Deepen its understanding of the cultural nuances.
The fundamentals remain strong, and the opportunity is still very real!
(This write-up is for educational/informational purposes only; happy to amend inaccuracies, if any. Views are personal.)
First published on LinkedIn, see the original.All writing →