China’s Narrowbody Pivot
I flew the COMAC C919 a couple of weeks ago. Here’s what I saw - and why it matters.
Whether or not the Boeing embargo holds, one thing is clear: the Airbus–Boeing duopoly in China is nearing its end. This isn’t just a geopolitical fallout - multiple indicators point to a structural realignment.
The Demand Landscape (2024-2043)
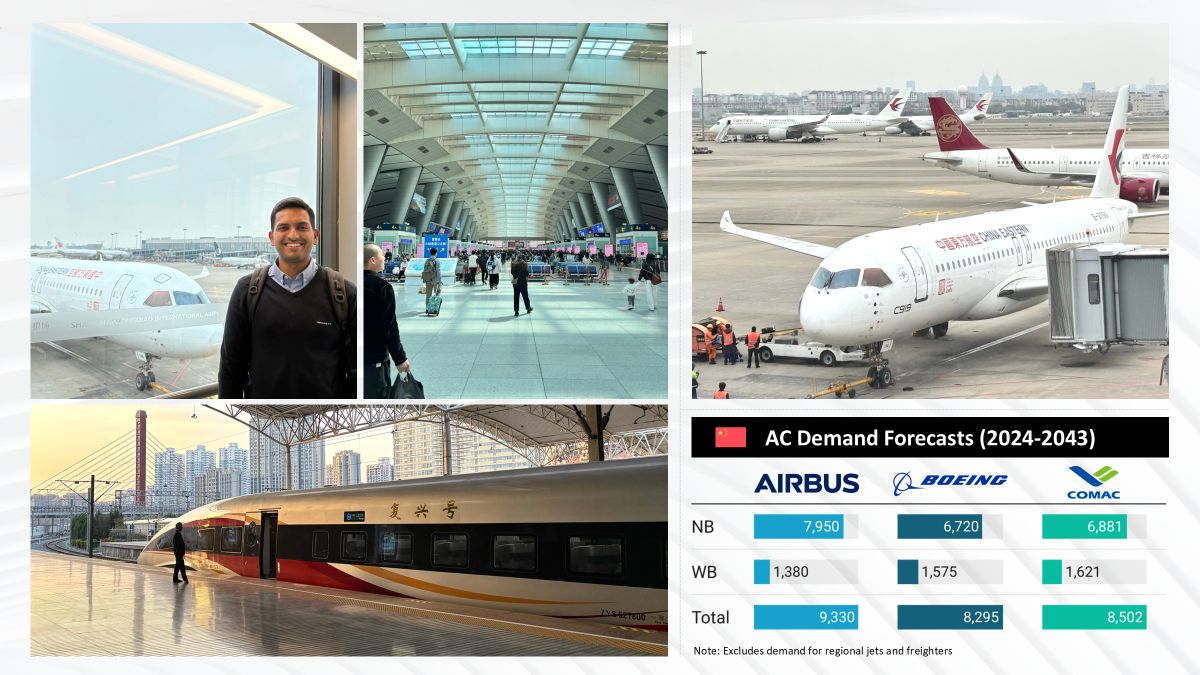
NB aircraft demand according to latest OEM forecasts:
COMAC: 6,881
Airbus: 7,950
Boeing: 6,720
That’s ~344 narrowbodies per year based on COMAC's projection. Even if the embargo lifts, Boeing risks being structurally edged out in the long term.
From AB to ABC (Airbus–Boeing–Comac) - How Capacity is Shaping Up
COMAC Ramp-Up (as shared with suppliers):
2025: 75 aircraft
2026–2028: 100/year
2029 onward: 150+/year
Airbus Tianjin FAL:
2025: ~72 aircraft
2026 onward: 120+/year (with 2nd line)
(Assuming all go to Chinese carriers)
By 2030, COMAC + Airbus could deliver 270–300 NB jets/year, nearly covering China’s annual demand, even without Boeing.
Made in China 2025: This Was No Accident, and China Saw This Coming
The C919 is a product of the Made in China 2025 initiative, aimed at high-tech self-reliance. This is the same industrial playbook that made China a global leader in EVs and high-speed rail - both once underestimated, are now world-leading in scale, quality, and innovation.
And it doesn't stop there:
>The C929 widebody is in early development.
>The CJ-1000A engine, which aims to replace the LEAP-1C is being tested, propelling China toward full-stack control.
Personal take
I flew the C919 on China Eastern, and the PaxEx felt on par with Airbus or Boeing (my wife couldn't even tell the difference). Yes, it still relies on Western components, but China is rapidly building a vertically integrated ecosystem through JVs and and targeted tech transfer.
HSR will substitute the need for domestic air travel
90% of airline capacity in China is domestic, and HSR continues to eat into it.
I took the Beijing–Shanghai HSR (~1300 KMs in 4 hrs) - faster door-to-door than flying. PEK–SHA remains one of the world’s busiest routes (7.7M seats in 2024), but when CR450 trains launch this year (up to 400 km/h), it will narrow the gap even further.
China now operates 48,000 KMs of HSR, with about 3,000 KMs being added on average every year. In that context, real AC demand may be softer than OEM forecasts.
Bottom Line
COMAC has the product, state backing, and a captive market! Would that be enough to succeed? Do share your thoughts!
(This write-up is for educational/informational purposes only; happy to amend inaccuracies, if any. Views are personal.)
#c919 #comac #aviation #madeinchina2025
First published on LinkedIn, see the original.All writing →